Category: AI and Critical Technology

  • Building the Electro-Industrial Investment Pipeline: A Recap from Basalt

    Building the Electro-Industrial Investment Pipeline: A Recap from Basalt

    A joint convening with CREC and RMI brought together state energy offices and economic development organizations to tackle one of the biggest opportunities in state economic development today: the electro-industrial era.


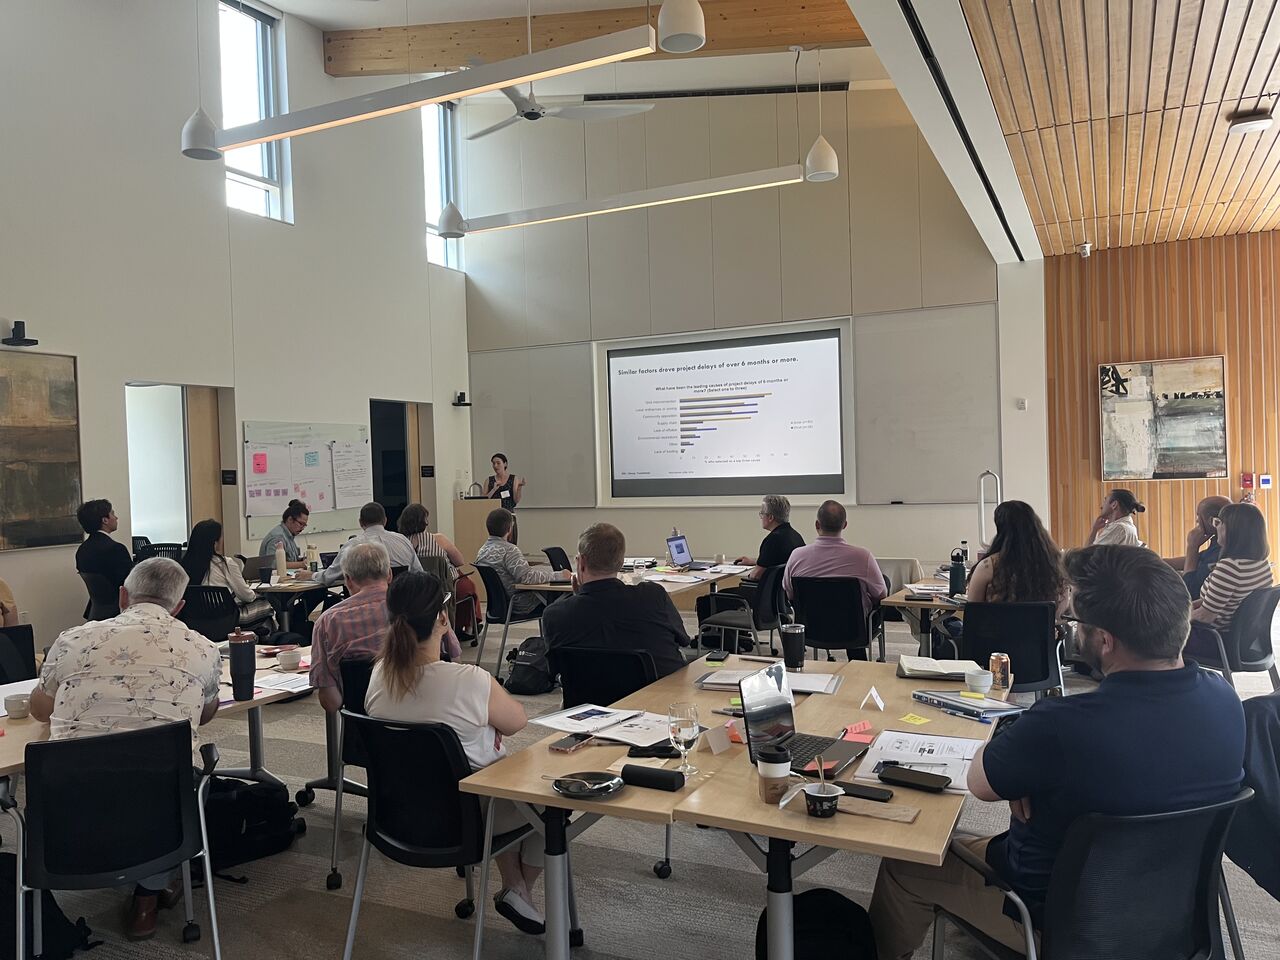
    In July, the Center for Regional Economic Competitiveness (CREC) partnered with the Rocky Mountain Institute (RMI) to host a three-day Electro-Industrial Investment Workshop in Basalt, Colorado. This workshop brought together representatives from State Energy Offices (SEOs) and state economic development organizations (EDOs) from nine states. The goal was to help states build the coordination, knowledge, and action plans needed to attract and grow investment in manufacturing, grid infrastructure, and power-dense industrial projects. The electro-industrial era marks the convergence of clean energy, smart manufacturing, and electrified infrastructure into a unified industrial stack, and ensuring states are prepared is important. CREC was a strong partner for RMI given its management of the State Economic Development Executives (SEDE) network.

    Why This Matters for State EDOs

    Energy and economic development touch the same investment decisions, but the two activities aren’t always coordinated inside state government. As data centers, advanced manufacturing, and other energy-intensive industries reshape site selection and readiness, that coordination and alignment matters more than ever. States that pair predictable permitting and siting with proactive grid planning and thoughtful incentive design are best positioned to compete for these projects.

    A recent CREC white paper  The Digital Backbone: Data Centers, Community Tradeoffs, and Regional Competitiveness, frames the challenge well. It argues that large power users like data centers are best understood as enabling infrastructure (comparable to ports, airports, and electric grids) whose value comes less from the direct jobs on site and more from the economic activity they support elsewhere: cloud services, advanced manufacturing, research computing, and the broader digital economy. That framing cuts both ways. It means these projects deserve to be evaluated on more than headline job counts, but it also means the tradeoffs — electricity costs, water use, land use, and who bears the cost of new infrastructure — are real and shouldn’t be waved away.

    The paper’s core argument is that good governance is itself becoming a competitive advantage: the states and regions that pair transparent, evidence-based decision-making with fair cost allocation and durable public trust are the ones best positioned to benefit from this wave of investment. Getting there requires exactly the kind of coordination this workshop was built around, with SEOs and EDOs working from a shared strategy, rather than making decisions about the same projects from separate silos.

    The workshop’s three objectives captured this well:

    1. Equip state teams with actionable best practices for building an electro-industrial investment pipeline.
    2. Lay the foundation for a State SEO–EDO community of practice, so states can keep learning from each other after the event ends.
    3. Produce tangible outcomes for every state team — including the start of a State Electro-Industrial Action Plan and 1–2 prioritized policy solutions with clear next steps.

    Key Pieces for State Economic Development Leaders

    A few of the ideas and tools referenced throughout the workshop are worth understanding in more depth for state EDO teams building their own electro-industrial strategy.

    Advanced Industrial Zones (AIZs)

    AIZs are a place-based policy model designed to solve one of the biggest bottlenecks in industrial development: the fact that a single large project — a chip fab, a battery plant, a green steel facility — has to clear municipal, county, state, and federal approvals separately, often with no coordination between them. The AIZ model instead pre-designates specific areas where a state (or state-community partnership) proactively lines up the pieces a manufacturer needs before a project ever applies: streamlined and often single-point permitting, coordinated infrastructure (power, water, rail, roads), and workforce development pipelines tied to the industries the zone is targeting. Learn more here: https://www.industrialzones.org/

    Energy zones more broadly

    “Energy zones” is a catch-all for a growing set of geographic designations that unlock funding, tax treatment, or streamlined permitting for projects sited within their boundaries. For state EDOs building an electro-industrial pipeline, understanding which designations exist in your state and how different designations such as Opportunity Zones, DOE-designated Energy Communities, and state-designated enterprise or industrial zones stack is increasingly a core part of site strategy, since the strongest packages often come from projects that qualify for more than one. The practical next step for a state EDO is mapping which of these overlap with existing priority sites and industries in-state.

    A few examples illustrate how this has worked in practice:

    • Texas’s Competitive Renewable Energy Zones (CREZ), 2005: The Texas legislature directed its public utility commission to designate priority wind-resource zones and build the transmission needed to connect them to load centers, rather than waiting for individual developers to justify transmission investment project by project. The state approved 3,600 miles of new 345 kV transmission in advance of generation, which helped unlock 15 GW of new wind capacity within a decade and cut wind curtailment by 16.5 percent within five years.
    • Illinois’s own Renewable Energy Access Plan: Because Illinois sits inside two multi-state grid operators (PJM and MISO) and can’t unilaterally direct regional transmission expansion, the Illinois Commerce Commission designated its own renewable energy zones based on resource potential, developer interest, and land use so the state could use those designations to engage PJM and MISO.

    Siting and permitting reform

    Permitting speed is consistently one of the biggest bottlenecks between a state winning a project and losing it to grid delays or approval uncertainty. States are experimenting with a few approaches:

    • Consolidating review. Rather than requiring a project to clear separate municipal, county, and state processes sequentially, some states are moving toward single-point-of-contact or concurrent-review models.
    • Pre-clearing sites. “Shovel-ready” or certified site programs where a state or regional EDO has already completed environmental assessments, utility studies, and zoning clearance before a company ever shows up can compress a multi-year siting timeline into months.
    • Setting clear standards up front, especially for energy infrastructure. Oregon’s Energy Facility Siting Council process, used for large solar, storage, and other energy facilities, is one example of a state permitting body with defined statutory criteria and timelines, paired with negotiated community benefit commitments.

    RMI has developed a State Permitting Power Tool to help states move past treating “permitting reform” as a single goal and instead identify exactly which problem they’re facing. The tool sorts challenges into high-level categories — things like fragmented governance and authority, community opposition and social acceptance, or unclear jurisdictional boundaries — and then surfaces relevant reforms for each one, drawn from real examples across states.  The tool helps policymakers identify potential state-level permitting reforms that could be employed to address these permitting challenges.

    Load growth and grid readiness

    As of mid-2026, roughly two dozen states have approved at least one “large-load tariff” — a special utility rate class for very large electricity customers. The core policy problem these tariffs are trying to solve: when a single customer needs 50, 100, or 500+ megawatts, the utility often has to build new generation, transmission, or distribution infrastructure to serve them. Without a large-load tariff, those costs can get spread across all ratepayers, including residential customers, even if the large project never materializes or leaves early. Ohio, Georgia, Texas, and Oregon are cited examples of different approaches to this problem.

    Incentive design: what the research says

    Tim Bartik of the W.E. Upjohn Institute, who presented at the workshop, recently co-published a multi-state study on whether clean energy incentives actually pay off for residents, conducted in partnership with RMI. The study examined 50 of the largest clean energy projects nationally. A few of the key findings are directly relevant to any state building an incentive strategy for electro-industrial investment:

    • Project type matters. EV and battery manufacturing projects had a median benefit-cost ratio well above wind, solar, and clean fuels projects. The gap comes down to jobs: EV/battery projects tend to create far more direct employment per dollar of incentive.
    • Bigger incentive packages don’t mean better outcomes. The 10 projects with the highest ratio of incentives to jobs all had lower benefit-cost ratios, meaning the largest deals were disproportionately likely to be bad deals for residents.
    • How an incentive is delivered matters as much as how much. Structuring incentives as specialized services — workforce training, infrastructure improvements — rather than straight cash improves cost-effectiveness by about 50%.

    Read more here: https://www.upjohn.org/research-highlights/new-study-incentives-most-clean-energy-projects-yield-positive-economic-return

    Next Steps

    The workshop was explicitly framed as the start of a longer conversation, not a one-off event. RMI and participating states are laying the groundwork for an ongoing SEO–EDO community of practice, which will become a standing space for peer learning, shared troubleshooting, and continued refinement of state action plans as they move from planning into implementation.

    For state economic development organizations, electro-industrial investment is no longer just an energy policy conversation or just an economic development conversation. It’s both, at the same time, and the states that build that early will have a real advantage in the years ahead.

  • The Digital Backbone: Data Centers, Community Tradeoffs, and Regional Competitiveness

    Data centers are the most visible physical form of the AI economy. They are arriving faster than many states and communities can evaluate them. They bring billions in private investment, expand local tax bases, and fund grid, fiber, and water improvements. But they also raise questions about electricity demand, water use, air quality, and whether communities get fair value for the incentives they grant.

    This white paper offers state, regional, and local leaders a grounded, evenhanded account of both sides. It argues that data centers are best understood as enabling infrastructure—like ports, airports, and electric grids—whose value lies in the economic activity they support rather than the handful of permanent jobs they create. Drawing on new causal research, case studies from Loudoun County to Lenoir to Lancaster, and the wave of legislation now moving through more than 30 states, the paper shows why benefits concentrate where deals are well structured and thin where communities accept investment figures at face value.

    With data center development shifting toward rural areas that often have the least capacity to assess the tradeoffs, the paper lays out the questions leaders should be asking, principles for responsible decision-making, and the distinct roles state, regional, and local leaders each play. Above all, it makes the case that public trust and sound governance are themselves competitive assets in the age of AI.

    Read the full white paper to see how your state or region can turn a contentious moment into lasting prosperity. 

  • CREC Blog: What Communities Should Know About Data Centers

    CREC Blog: What Communities Should Know About Data Centers

    The race to build data centers is reshaping local economies faster than almost any other real estate trend. From 2023 to 2024, data center construction spending increased by 70%, more than triple the rate of any other property type. The sector is drawing billions in venture capital and now consumes up to eight percent of total U.S. electricity.

    For local communities, that growth is arriving with both a windfall and a set of tradeoffs: improved fiber and broadband networks, short-term and permanent job gains, and large tax receipts on one side, with infrastructure demands, public health concerns, and general local opposition on the other. Data centers are coming; the question is how economic developers can help communities capture the benefits and manage the tradeoffs.

    Why are there so many new data centers?

    A data center is a facility used to house large computer systems. There are many types of data centers hosting different services, but today’s headline centers are mostly used for cloud computing, including massive hyper scalers, which host at least 5,000 servers and can be 60,000 square feet in size. Cloud computing is an on-demand computing service, which can be rented by consumers. These centers are used for various IT purposes like storage, networking, and software deployment.

    Separately, AI training data centers use cloud-computing’s on-demand infrastructure with specialized hardware and storage to train Large Language Models (LLMs), like ChatGPT. The AI market is booming and driving data center growth through investments by such companies as Microsoft, OpenAI, Google, and AWS. As these companies search for sites, EDO leaders are often the ones asked to explain what a data center will mean for a community. This piece is built for those conversations: a guide to the benefits, costs, and tradeoffs that come up when a project is proposed.

    Read More on the CREC Website Here.

  • Brookings: Turning the data center boom into long-term, local prosperity

    The AI goldrush roars on. Hyperscalers like Google and artificial intelligence (AI) upstarts like OpenAI continue to pour massive sums into building gargantuan data centers, often in small- and medium-sized communities.

    As the deals proliferate, concerns are rising about the huge amounts of electricity and water required to keep the centers running. At the same time, pitched battles over zoning and permitting rules are pitting tech-firm developers against local land-use managers, especially in rural and exurban America.

    Yet beyond such infrastructure and resource concerns, sharp debates are also engulfing the facilities’ core economic proposition for communities. Local leaders are questioning the credibility of Big Tech’s promises of spillover effects that will produce high-quality economic development beyond near-term construction. What’s more, skeptics are wondering about the veracity of the developers’ assurances of a thrilling new era of “reindustrialization” across Main Street America.

    These debates raise fundamental questions: To what extent are the data center builders’ promises of economic development more than hype? And if these promises are more than hype, how can communities make sure these pledges translate into a durable local economic advantage?

    Continue reading here.

  • AMCC: 10 Questions SMEs Should Ask About Data Centers

    During a February 6, 2026 AMCC call, Dr. Deborah Stine provided an excellent discussion on data centers and advanced manufacturing.

    To view the presentation recording (her presentation begins at the 11:30 mark) and slides, click here.


    The American Manufacturing Communities Collaborative (AMCC) is designed to create and strengthen an alliance of communities with regional economic development initiatives underway dedicated to achieving sustainability through economic growth, improved environmental performance, and inclusive well-paid job creation supporting initiatives to create new opportunities and equity within a revitalized American manufacturing base.

    Read more here.

  • A.I. in Economic Development: Transforming Strategies and Boosting Results

    Who wouldn’t want to make economic development initiatives better and faster? A.I. has the potential to radically economic development across the board.

    A.I. understandably raises important questions about the future of work, productivity, and—specifically for the State Economic Development Executives (SEDE) Network—their potential impact on the field of economic development. And for good reason, experts estimate that A.I. could contribute between $4 trillion and $7 trillion annually to the global economy and that efficiency gains from A.I. could take full effect by as early as 2040.

    But what does this mean for economic development leaders and how might these gains be leveraged to improve economic performance at the state level? This was the central question of the SEDE Network’s October 24th webinar: “The Role of A.I. in Economic Development”. The webinar featured Erik Vasilauskas from the W.E. Upjohn Institute and Jeff DeBellis and Maggie Smith from the North Carolina Department of Commerce.

    Erik’s presentation explored the impact of A.I. on various occupations and the labor market generally, drawing on data from the O*NET Work Activities Survey and a Pew Research Center study. The research revealed key insights:

    • Three clusters based on A.I. exposure: low, medium, and high
    • High-exposure occupations tend to have greater educational attainment
    • Many high-exposure roles requiring a bachelor’s degree or higher are expected to grow (2023-2033)

    Interestingly, despite concerns about A.I.’s impact on white-collar jobs, employment in these professions has slightly increased since the pandemic, aligning with Census Bureau findings that suggest A.I. use is not linked to job declines and may foster growth.

    Meanwhile, Jeff and Maggie’s presentation on A.I. in economic development explored how artificial intelligence is set to transform the field of economic development specifically. The presentation highlighted:

    • Benefits of A.I. to economic developers, who may increase their productivity
    • Practical applications: idea generation, data summarization, and writing assistance
    • Comparison of various A.I. platforms
    • Importance of critically evaluating A.I.-generated responses

    Jeff and Maggie underscored A.I.’s potential to significantly boost productivity and decision-making in economic development while advocating for responsible use of these technologies.

    These presentations demonstrate A.I.’s transformative potential for the field of economic development and the U.S. economy more broadly. The insights shared by Erik Vasilauskas, Jeff DeBellis, and Maggie Smith underscore both the challenges and opportunities that A.I. presents for economic development professionals. While concerns about job displacement are valid, evidence suggests that A.I. is more likely to enhance productivity and complement existing roles, particularly in knowledge-intensive sectors.

  • Webinar: The Role of AI in Economic Development

    Join the SEDE Network for this webinar on the role of Artificial Intelligence (AI) in economic development. This presentation from Jeff DeBellis and Maggie Smith from the North Carolina Department of Commerce and Erik Vasilauskas from the W.E. Upjohn Institute for Employment Research, will cover general trends and specific applications of AI in economic development.

    Erik Vasilauskas is a Research Analyst at the W.E. Upjohn Institute for Employment Research

    Jeff DeBellis is the Director of Economic & Policy Analysis in the NC Department of Commerce’s Labor & Economic Analysis Division

    Maggie Smith is a Research Analyst at the NC Department of Commerce

    Webinar Materials

    The recording of this webinar is available to watch here.

    The slide deck from North Carolina Commerce is available here.

    The slide deck from The W.E. Upjohn Institute is available here.

    The results from the in-webinar poll are available here.